SORA RENTAL NOTE · 43
Can a foreign student get a loan for a rental deposit?
Check a Korean deposit loan’s borrower, visa and property conditions before budgeting or paying a contract deposit.
Content checked · 3 October 2026
The key points
- Eligibility belongs to a specific loan product, not to all Residence Card holders.
- Your visa, income and the intended property need separate checks.
- Budget from the lender’s actual decision, not an advertised maximum.
01 — 04
Start with the comic
Documents and screens are simplified illustrations. Check the sources below for actual forms and steps.
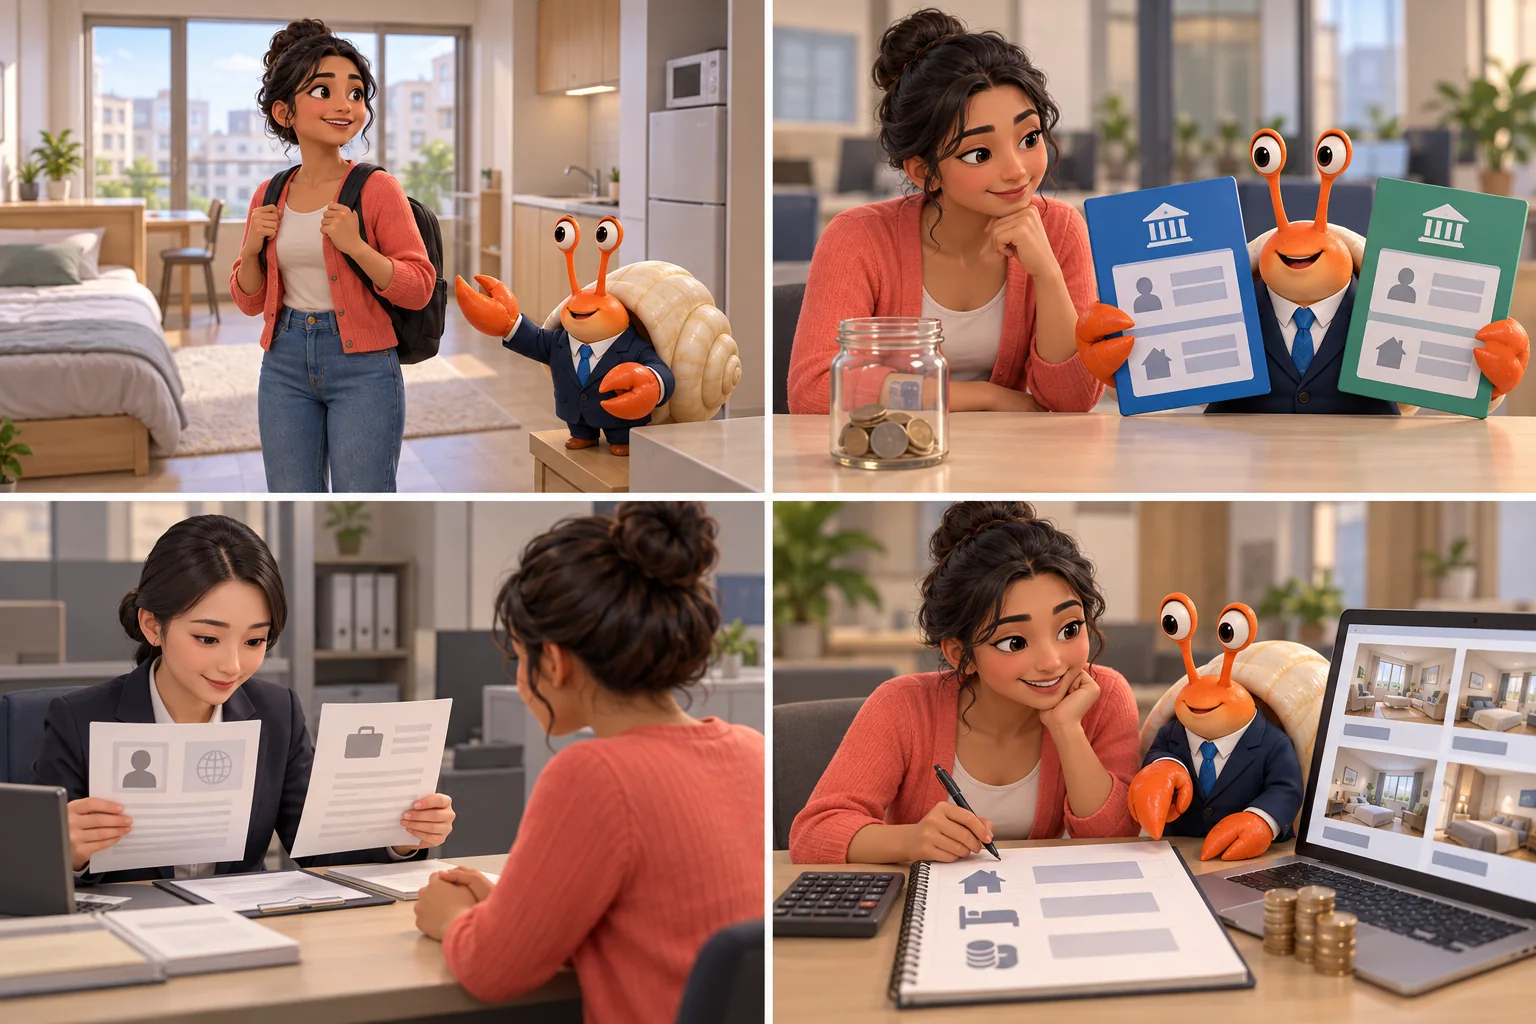
My savings will not cover this apartment’s deposit. Can I borrow the rest?
These loan products have different eligibility rules.
I will ask the bank to check my status, income and this property.
Choose a budget using the amount and timing actually confirmed.
Read the exact foreign-applicant condition
- Immigration status
- Eligibility
- Guarantee product
A Residence Card is not a general entitlement to a deposit loan. For example, Hana Bank’s Uryang Housing Jeonse Loan describes a foreign-applicant condition involving domestic residence reporting (국내거소신고), eligibility for Seoul Guarantee Insurance and remaining visa validity. Do not read that wording as covering every foreigner who completed ordinary foreigner registration.
Another Hana deposit-loan product explicitly excludes foreign nationals. These contrasting examples show why a blog headline saying “loans for foreigners” is not enough. Ask the bank about your exact immigration status, including D-2 if relevant, and obtain the name of a product that actually accepts that status before building a budget around it.
The borrower and the property both need checking
- Applicant conditions
- Property type
- Loan assessment
Ask what income evidence, repayment assessment and guarantee review the lender needs. Show the actual property and proposed lease: an eligible applicant may still choose a property or contract outside the product’s conditions. An advertised maximum is not your personal approval or expected amount.
Budget for your own contribution, rent, other housing costs, interest and repayment. Confirm when the loan can be disbursed and whether it goes to the landlord. Compare obligations you understand, rather than choosing a room because an online calculator displays a large number.
Agree the sequence before paying a contract deposit
- Loan assessment
- Cancellation terms
- Refund conditions
Ask which checks can happen before signing and which require an executed lease or payment evidence. Do not pay on the assumption that approval is certain. Tell the realtor and landlord when funding remains conditional so the contract timetable reflects that uncertainty.
If you need the agreement to end and the contract deposit to be returned when financing fails, negotiate clear written terms before paying. Discuss the exact loan, application deadline, refusal evidence and refund procedure. Do not assume a rejected loan automatically cancels a lease or guarantees that money already paid will come back.
What to check
- Identify a current product that accepts your exact status.
- Ask the lender to check both you and the intended property.
- Confirm the likely amount, costs, disbursement timing and repayment duties.
- Agree any financing condition in writing before paying.
Common questions
Does a deposit-return guarantee mean the bank will lend to me?
No. A loan provides borrowed funds; a deposit-return guarantee addresses a different risk. Eligibility for one does not establish approval for the other.
Does having a long time left on my visa make approval certain?
No. Visa validity is only one possible condition. The product’s applicant category, underwriting, guarantee and property requirements still need to be satisfied.
Official sources
Korean laws and guidance from public agencies, universities and service providers. Most originals are in Korean or English. School and product examples apply only within their stated scope.